

Russia Enzyme Modified Cheese Market Size, Share, and Growth Forecast, 2025 - 2032
Acrylic Fibre Market by Form (Staple Fibre and Filament Fibre), Blend (Acrylic-Wool, Acrylic-Viscose, Acrylic-Nylon, Acrylic-Cotton, and Others), End Use Industry (Textiles & Apparel, Furniture & Upholstery, Industrial, Building & Construction, Automotive, and Others), Regional Analysis from 2025 to 2032

November 2025
Author : Rajat Zope
Chemicals & Materials
Acrylic Fibre Market Size and Share Analysis
The global acrylic fibre market size is likely to value at US$ 5.9 billion in 2025 and is projected to reach US$ 8.2 billion, growing at a CAGR of 4.9% between 2025 and 2032.
Increasing demand for wool-like synthetic alternatives in apparel applications and growing adoption of sustainable production technologies, including recycled acrylic fibres and bio-based formulations, are some of the key factors bolstering the growth of the global acrylic fibre market.
Key Industry Highlights
- Regional Leaders : Asia Pacific dominates global acrylic fibre consumption with 60% market share driven by massive textile manufacturing and expanding domestic demand across China and India.
- Dominant Grades: India represents fastest-growing regional market with 4.9% CAGR through 2035 supported by textile industry expansion and rising middle-class consumption patterns.
- Leading Segments : Staple Fibre form maintains dominant position with 75% market share due to versatility across apparel, home furnishing, and industrial textile applications.
- Blends : Acrylic-Wool blends represent fastest-growing segment with 4.1% CAGR driven by optimal performance characteristics and cost advantages over natural alternatives.
- Market Drivers : Sustainable fibre development including recycled content achieving 75% recycled acrylic creates premium market opportunities aligned with circular economy initiatives and environmental regulations
| Key Insights | Details |
|---|---|
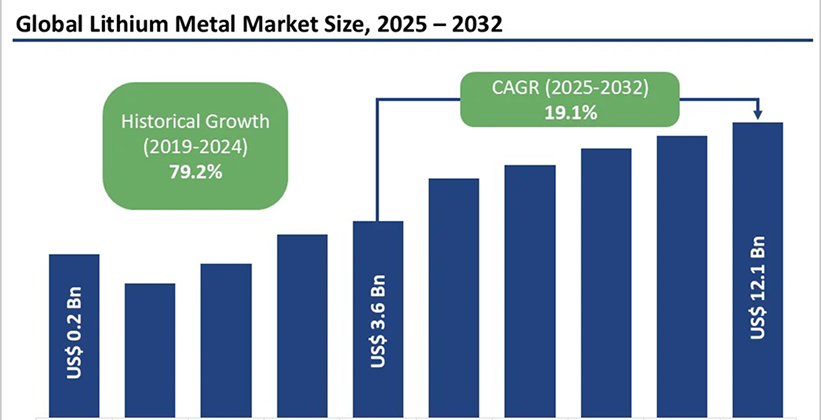
| Lithium Metal Market Size (2025E) | US$3.6 Bn |
| Market Value Forecast (2032F) | US$12.1 Bn |
| Projected Growth (CAGR 2025 to 2032) | 19.1% |
| Historical Market Growth (CAGR 2019 to 2024) | 79.2% |
Market Factors - Growth, Barriers, and Opportunity Analysis
Advanced Battery Technology Adoption Fueling Lithium Demand
The rapid adoption of lithium-metal anode battery technology is a significant driver for this market. Lithium metal batteries offer superior energy density and longer cycle life compared to traditional lithium-ion batteries, making them increasingly attractive for electric vehicles and grid storage applications.
According to the U.S. Department of Energy (DOE), the energy density in lithium metal anodes is approximately five times that of graphite anodes traditionally used in lithium-ion cells, offering significant mileage extension for EVs. The International Energy Agency (IEA) data shows that the global electric car stock already exceeded 17 million in 2024, implying a considerably increased demand for high-purity lithium metal components essential for next-generation battery manufacturing.
Regulatory emphasis on reducing carbon emissions and meeting climate goals, such as the European Union (EU)’s Fit for 55 package, drives governments and original equipment manufacturers (OEMs) to quicken the adoption of energy-efficient battery solutions, thus propelling the market growth. These factors, combined with breakthroughs in solid-state battery commercialization, position lithium metal as a critical raw material for future energy systems development
Complex Supply Chain and High Production Costs Limiting Scalability
The lithium metal market faces significant structural challenges due to its complex production process involving electrolysis of lithium chloride and demand for high-purity materials.
Manufacturing lithium metal requires stringent quality control and advanced handling protocols to manage its high reactivity and flammability, resulting in elevated capital expenditures and operational costs. According to industry data from the U.S. Geological Survey (USGS) and market analysts, production costs for lithium metal remain 20-30% higher than those for lithium compounds such as lithium hydroxide or carbonate.
This cost disparity limits lithium metal’s price competitiveness, especially when raw material supply is concentrated in brine-rich regions such as the Lithium Triangle of South America.
Stringent environmental regulations governing mining and chemical extraction processes, particularly in the EU and North America, impose additional compliance costs and extend lead times. These supply chain and cost barriers pose risks to scaling production volumes rapidly enough to meet growing demand, potentially constraining market growth in the short to medium term.
Complex Supply Chain and High Production Costs Limiting Scalability
The lithium metal market faces significant structural challenges due to its complex production process involving electrolysis of lithium chloride and demand for high-purity materials.
Manufacturing lithium metal requires stringent quality control and advanced handling protocols to manage its high reactivity and flammability, resulting in elevated capital expenditures and operational costs. According to industry data from the U.S. Geological Survey (USGS) and market analysts, production costs for lithium metal remain 20-30% higher than those for lithium compounds such as lithium hydroxide or carbonate.
This cost disparity limits lithium metal’s price competitiveness, especially when raw material supply is concentrated in brine-rich regions such as the Lithium Triangle of South America.
Stringent environmental regulations governing mining and chemical extraction processes, particularly in the EU and North America, impose additional compliance costs and extend lead times. These supply chain and cost barriers pose risks to scaling production volumes rapidly enough to meet growing demand, potentially constraining market growth in the short to medium term.
Market Factors - Growth, Barriers, and Opportunity Analysis
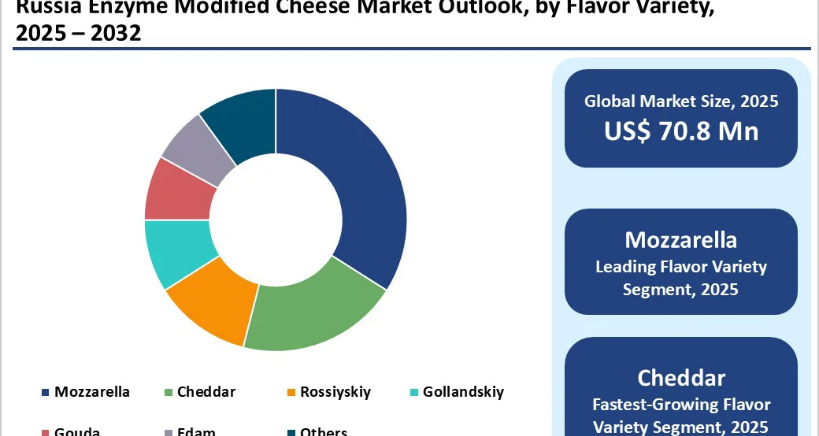
Flavor Variety Insights - 34% of the Russia enzyme modified cheese market revenue share in 2025
Mozzarella is commanding market leadership, capturing an estimated 34% of the Russia enzyme modified cheese market revenue share in 2025. This dominance is fundamentally driven by Mozzarella's position as Russia's leading cheese variety in the broader cheese market, propelled by the explosive growth of pizza consumption and Italian-cuisine-inspired prepared foods across urban markets.
The rapid expansion of both domestic and international pizza chains operating in Russia, including Domino's Pizza, Dodo Pizza, and Papa John's local franchises, has created sustained industrial demand for cost-effective Mozzarella flavor solutions, positioning enzyme-modified cheese as an economically advantageous alternative to expensive fresh or processed Mozzarella in high-volume pizza production applications.
The technical characteristics of Mozzarella-style EMC also align exceptionally well with Russian food manufacturers' operational requirements.
Cheddar-style enzyme modified cheese represents the fastest-expanding flavor variety segment throughout the 2025 - 2032 forecast period. This strong growth momentum is driven by evolving Russian consumer preferences toward sharper, more pronounced cheese flavor profiles characteristic of Western-style snack foods, particularly cheese-flavored potato chips, crackers, and extruded snack products, where Cheddar represents the archetypal flavor benchmark.
The expansion of the snacks market in Russia is producing incremental demand for Cheddar-style EMC as flavor coating applications and seasoning blend formulations, where the ingredient's intense flavor delivery at low dosage rates provides significant cost advantages compared to natural aged Cheddar cheese powder alternatives. The exceptional growth of the segment is further amplified by the versatility of Cheddar across diverse food processing applications beyond traditional snack categories
Flavor Variety Insights - 34% of the Russia enzyme modified cheese market revenue share in 2025
Mozzarella is commanding market leadership, capturing an estimated 34% of the Russia enzyme modified cheese market revenue share in 2025. This dominance is fundamentally driven by Mozzarella's position as Russia's leading cheese variety in the broader cheese market, propelled by the explosive growth of pizza consumption and Italian-cuisine-inspired prepared foods across urban markets.
The rapid expansion of both domestic and international pizza chains operating in Russia, including Domino's Pizza, Dodo Pizza, and Papa John's local franchises, has created sustained industrial demand for cost-effective Mozzarella flavor solutions, positioning enzyme-modified cheese as an economically advantageous alternative to expensive fresh or processed Mozzarella in high-volume pizza production applications.
The technical characteristics of Mozzarella-style EMC also align exceptionally well with Russian food manufacturers' operational requirements.
Cheddar-style enzyme modified cheese represents the fastest-expanding flavor variety segment throughout the 2025 - 2032 forecast period. This strong growth momentum is driven by evolving Russian consumer preferences toward sharper, more pronounced cheese flavor profiles characteristic of Western-style snack foods, particularly cheese-flavored potato chips, crackers, and extruded snack products, where Cheddar represents the archetypal flavor benchmark.
The expansion of the snacks market in Russia is producing incremental demand for Cheddar-style EMC as flavor coating applications and seasoning blend formulations, where the ingredient's intense flavor delivery at low dosage rates provides significant cost advantages compared to natural aged Cheddar cheese powder alternatives. The exceptional growth of the segment is further amplified by the versatility of Cheddar across diverse food processing applications beyond traditional snack categories
Competitive Landscape
The Russia enzyme-modified cheese market landscape exhibits a moderately consolidated competitive structure characterized by the presence of both international ingredient suppliers maintaining limited operations and an emerging base of domestic and regional players positioned to capitalize on supply chain disruptions affecting Western multinationals. Market concentration analysis indicates that the top five suppliers collectively command approximately 55-60% market revenue share, with the remaining distributed among smaller regional distributors, specialty ingredient suppliers, and direct importers serving niche customer segments. This concentration level is indicative of the technical expertise, regulatory compliance capabilities, and established customer relationships required to successfully compete in the enzyme-modified cheese ingredients space. Key Industry Developments
Key Industry Developments
In September 2025, Kerry Group expanded its long-standing Russian presence by opening a new plant in the Istra district of Moscow. Designed to produce ingredients for meat processing and snacks, the facility has a 26,000-ton annual capacity and uses locally sourced raw materials to supply Russia and nearby markets. This move follows Kerry’s 2014 regional development and application center, strengthening its strategic footprint in the region. In August 2025, Russia reported a 16% rise in dairy exports, following an 18% increase in 2024. Key destinations include the Eurasian Economic Union, Uzbekistan, and China, with efforts to enter new markets. Strong growth was seen in cheese and curd (18%), fermented products (23%), ice cream (37%), and dried whey (over double). The government continues prioritizing export diversification. In July 2025, Jubilant FoodWorks Limited, the master franchisee for Domino’s Pizza in India and select regions, exited the Russian market by selling its 67.5% stake in Zodis Food Pvt Ltd. The move completes its withdrawal amid geopolitical and operational challenges. Zodis Food’s outlets were transferred to local management. Jubilant will now focus on strengthening growth across core markets such as India, Nepal, and Bangladesh, aligning with its strategic repositioning.
Companies Covered in Russia Enzyme Modified Cheese Market
- Kerry Group plc
- Aromsa A.S.
- Jeneil Biotech, Inc.
- Maysa Gıda San. ve Tic. A.Ş.
- Butter Buds, Inc.
- Advanced Enzyme Technologies Limited
- Sunson Industry Group Co., Ltd.
- EPI Ingredients
- DuPont Nutrition & Biosciences
- Edlong Dairy Technologies
- Agropur Ingredients
- Angel Yeast Co. Ltd.
- Biocatalysts Limited
- Döhler GmbH
- Sensient Flavors International
Frequently Asked Questions
The Russia enzyme modified cheese market is projected to reach US$70.8 Million in 2025.
Increasing demand for processed food and cost-effective cheese production is driving market growth.
Major companies include regional dairy producers and enzyme suppliers across Russia.
Related Reports
- Non-dairy Cheese Market
- Non-Dairy Ice Cream Market
- Libya Dairy Products Market
- Global Fermented Dairy Products Market
- Enzyme Modified Dairy Products Market
- Dairy Cream Market
- Grass Based Dairy Products Market
- Dairy-Free Yogurt Market
- Dairy Replacer Market
- Dairy Cultures Market
- Non-dairy Whipping Agents Market
- Dairy Derived Flavors Market
Industry Size (2025): USD 5.5 Billion
Media Citation




4000+
Reports Delivered
Get In Touch
Testimonials
“Persistence Market Research has helped us immensely in compiling a sound database. Our expectations were exceeded by their research team.”
Fortune 500 Telecom Company, USA

Second Floor, 150 Fleet Street, London, EC4A 2DQ.

UK Phone
+44 203-837-5656

108 W 39th Street, Ste 1006, PMB2219, New York, NY 10018
USA Phone
+1 646-878-6329

IT Unit No. 504, 5th Floor, Icon Tower, Baner, Pune - 411045.
APAC Phone
+91 906 779 3500

sales@persistencemarketresearch.com
7865443378
Persistence Market Research is a Trade Name of Persistence Research & Consultancy Services Limited.
Company Number: 15310893Quick Links
Our Partners
Secure Payments Through


Copyright © 2025 Persistence Market Research. All Rights Reserved

